
RDP 8909: Optimal Wage Indexation, Monetary Policy and the Exchange Rate Regime Appendix 3: Calculating the Variance of Θ
December 1989
- Download the Paper 753KB
Linearizing by a Taylor expansion around the estimated values of the parameters and variances reveals that
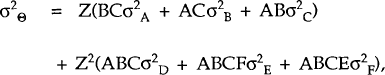
where:
| A | = | β4+β1β3, |
| B | = | β4β2 + β1(α + 1), |
| C | = | (1+ε)σ2u + εσ2x, |
| D | = | (β4β2)2(σ2ξ + σ2υ) + β24(σ2κ + σ2s) + β21(σ2δ + σ2τ), |
| E | = | A2, |
| F | = | C − σ2x, |
| Z | = | (D + EF)−1. |
Calculation of σ2A … σ2F requires knowledge of the variances of ε, β2, β3 and β4, which are not estimated. However, the variances of γ, π1, π2 and π5 are estimated, and the necessary variances can be approximated by using the “Delta method” (De Groot (1986), pp 429–430) viz. for a random variable x,
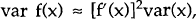
hence
 |
= |  |
 |
= |  |
 |
= | 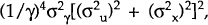 |
 |
= | 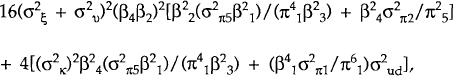 |
 |
= | 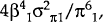 |
 |
= | 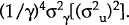 |